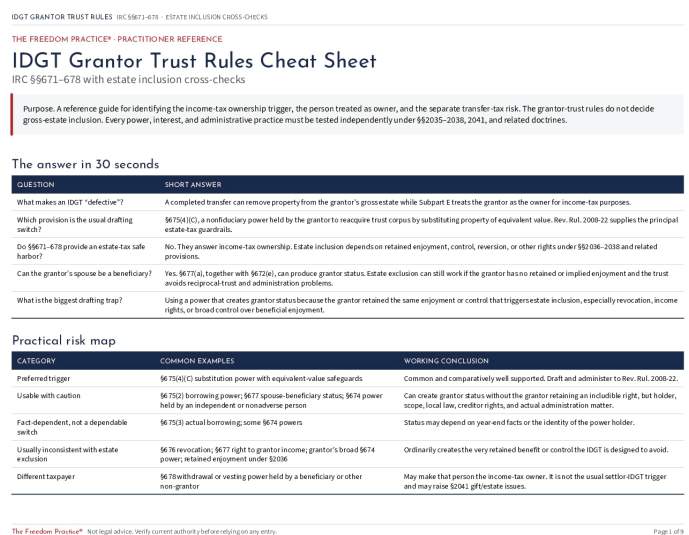
IRC §§671–678, mapped against the estate inclusion tests, on ten pages you can keep next to the drafting file.
Grantor trust status is the easy part. The hard part is proving that the same power that creates income-tax ownership does not pull the trust back into the gross estate. This reference lays both analyses side by side so you can check one against the other before the instrument goes out.